Explore by category
Is a HELOC a good idea?
In this article:
- How does a home equity line of credit (HELOC) work?
- What are the advantages and drawbacks of a HELOC?
- When is a HELOC a good idea?
- When might a HELOC not be a good idea?
- What are the alternatives to a HELOC?
- How can you decide if a HELOC fits your needs?
- Is a HELOC a good idea for you?
- FAQs about HELOCs
Quick answer: A HELOC may be a good idea if you want access to home equity over time and are able to manage the required monthly mortgage payments. Whether it makes sense depends on why you’re borrowing, your financial situation, and how you plan to repay what you use
Key Points
A home equity line of credit (HELOC) may let you borrow against your home equity as needed during a set draw period rather than taking the full amount upfront.
Most HELOCs have variable interest rates, which means your borrowing costs and monthly payments may change over time.
Because a HELOC is secured by your home, failing to meet the repayment requirements could ultimately put the property at risk.
If you’re considering a HELOC, the question isn’t just whether it’s a good idea, but whether it’s a good idea for you.
How you plan to use the money matters, but so does how you repay it. That includes both the monthly payments along the way and how you’ll ultimately repay the remaining balance.
Below, we’ll look at when a HELOC may be worth considering, when it may not, and what to consider before you decide.
Finance of America does not currently offer home equity loans or HELOCs.
How does a home equity line of credit (HELOC) work?
A HELOC is a revolving line of credit that lets you borrow against your home equity, repay what you borrow, and borrow again as needed. Your credit limit depends on factors such as your home’s value, mortgage balance, income, credit history, and the lender’s requirements. If you already have a first mortgage, the HELOC generally becomes a second lien on your home.
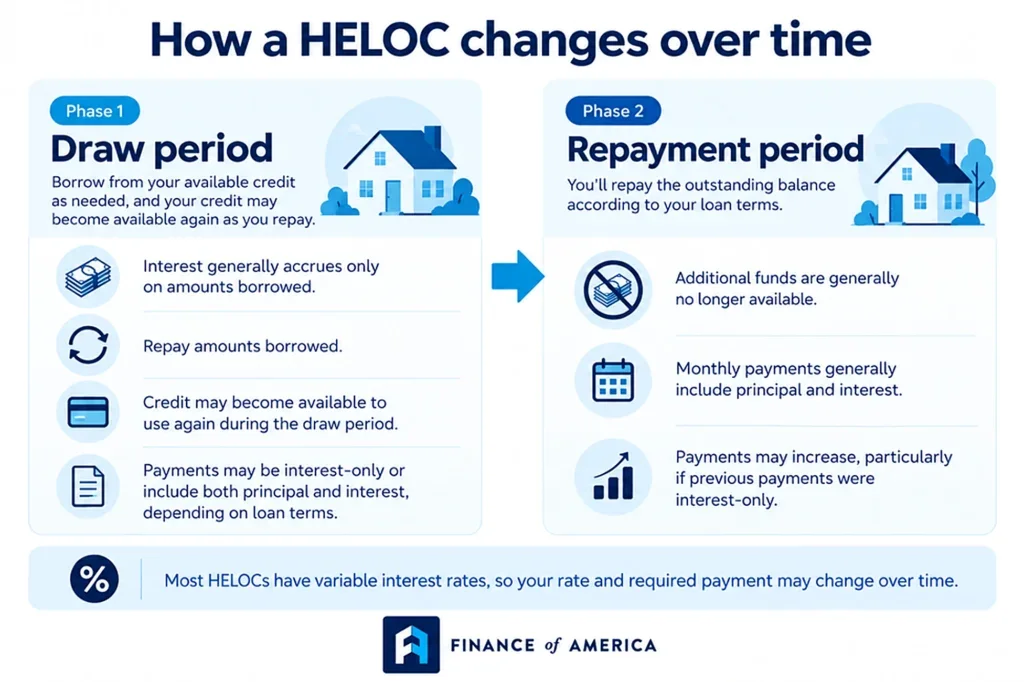
Here’s how a HELOC typically works:
- Draw period: You may borrow from your available credit as needed during a set period. As you repay what you’ve borrowed, that credit may become available to use again.
- Monthly payments: You typically pay interest only on the funds you’ve drawn. Depending on the loan terms, payments during the draw period may be interest-only or include both principal and interest.
- Interest rates: Most HELOCs have variable interest rates, so your rate and required monthly payment may change over time.
- Repayment period: After the draw period ends, you generally can’t borrow additional funds and must repay the outstanding balance. Your payments may increase, particularly if you previously made interest-only payments.
Because your home serves as collateral, failing to make the required payments could ultimately put the property at risk.
What does a HELOC cost?
HELOC costs vary by lender and may include application or origination fees, appraisal or valuation costs, annual fees, inactivity fees, or early-closure fees. Some lenders offer limited or no upfront closing costs, but may require you to keep the line open for a certain period.
When comparing offers, look beyond the advertised interest rate. Check the fees, how rates may change, when you’ll need to repay what you borrow, and whether you can switch to a fixed rate.
Finance of America does not currently offer home equity loans or HELOCs.
What are the advantages and drawbacks of a HELOC?
The features that make a HELOC useful in some situations may create downsides in others. Here are some of the key trade-offs to consider.
Potential advantages of a HELOC
- Access to funds as needed: You choose how much of your available credit to use.
- Interest based on the amount drawn: Interest is generally charged on the amount you draw, not your entire available credit line.
- Reusable credit: As you repay what you borrow, that credit may become available to use again during the draw period.
- Potentially lower rates than unsecured debt: Because your home secures the loan, HELOC rates may be lower than rates on some unsecured borrowing.
Potential drawbacks of a HELOC
- Home used as collateral: Missing required payments could ultimately put the property at risk.
- Variable payments: Most HELOCs have variable rates, so borrowing costs and required payments may rise or fall.
- Higher repayment-period payments: Monthly payments could increase when the draw period ends, especially if you previously made interest-only payments.
- Potential fees: Depending on the lender, you could pay closing costs or other fees.
- Reduced home equity: Borrowing more increases the debt secured by your home and reduces your remaining home equity.
- Changes to available credit: A lender may reduce your credit limit or stop you from borrowing more if your home’s value drops significantly or there are concerns about your ability to repay.
When is a HELOC a good idea?
A HELOC may make sense for some borrowing needs and be less suitable for others. The difference often comes down to how you plan to use the funds, the payments you’ll need to make, and how you’ll repay the balance. Here are some situations when a HELOC may make sense.
You need funds over time, or you aren’t sure how much you’ll need
A HELOC may make sense when expenses occur at different times or the final cost isn’t known upfront. If you’re completing home improvements in phases, for example, you may draw funds as bills come due rather than choosing a loan amount based on an estimate.
You can comfortably manage variable payments
A HELOC may be better if your budget can accommodate payments that change over time. If you’re approaching retirement, also consider whether those payments would remain manageable if your income or cash flow changes.
You have a clear repayment plan
A HELOC may make more sense if you know how you’ll repay what you use. Think about how you’ll manage payments throughout the loan, especially if they increase after the draw period ends.
You want to pay off higher-interest debt and understand the trade-offs
A HELOC may offer a lower interest rate than some other types of debt. However, using a HELOC to consolidate unsecured debt, such as credit card balances, replaces it with debt secured by your home. Consider whether the potential savings outweigh the added risk.
When might a HELOC not be a good idea?
There are also situations when taking out a HELOC may create more financial pressure than it solves. Before borrowing, consider whether any of the following apply to you.
Changing payments could strain your budget
With a variable-rate HELOC, the payment you start with may not be the payment you have later. A HELOC may be less suitable if you need predictable monthly expenses or if a higher payment would stretch your budget, particularly if you expect your income to decrease or become more fixed in retirement.
You need borrowed funds to cover ongoing household expenses
A HELOC may be less suitable for covering groceries, utilities, or other recurring household expenses. Repeatedly borrowing to cover those costs may increase your debt without closing the ongoing gap between your income and expenses.
You’re uncomfortable using your home as collateral
If you don’t want to take on additional debt secured by your home, a HELOC may not be the right fit. You may want to compare unsecured borrowing options, recognizing that their rates and terms may differ.
What are the alternatives to a HELOC?
A HELOC isn’t the only option if you need to borrow money or want to use some of your home equity. The right choice depends on how much you need, whether you want to keep your current mortgage, and what kind of monthly payments fit your budget.
Options to compare may include:
- Home equity loan: Generally provides a one-time lump sum, typically with a fixed interest rate and regular monthly payments.
- Cash-out refinance: Replaces your current mortgage with a larger loan, allowing you to receive the difference, minus applicable costs, in cash.
- Personal loan: Lets you borrow without using your home as collateral, although interest rates may be higher than with borrowing secured by home equity.
- Home Equity Conversion Mortgage (HECM): Allows eligible homeowners age 62 and older to access a portion of their home equity without required monthly mortgage payments.
- Proprietary reverse mortgage: Offers an alternative to FHA-insured HECMs, with different borrowing limits, costs, features, and requirements. Some products are available to homeowners as young as 55, depending on the product and state.
To learn more, please visit the CFPB’s “Reverse Mortgages: A Discussion Guide.”
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, such as property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
Finance of America does not currently offer home equity loans or HELOCs.
Each option has different costs, eligibility requirements, repayment terms, and effects on your home equity. Comparing those differences with what you need the money for may help you narrow down which choices are worth exploring further.
→ Learn more: HELOC alternatives: 7 ways to access cash
How can you decide if a HELOC fits your needs?
A few key questions may help you decide whether a HELOC makes sense for you.
| Ask yourself… | Why it matters |
| Do I need the money all at once or over time? | A HELOC is designed for borrowing at different times. If you need the amount upfront, a lump-sum option like a home equity loan may be worth considering. |
| How important is payment predictability to me? | Most HELOCs have variable rates. A fixed-rate option, such as a home equity loan, may be worth considering if you want more predictable payments. |
| Do I want to keep my current mortgage? | A HELOC generally works alongside your current mortgage, while a cash-out refinance replaces it. |
| Am I comfortable using my home as collateral? | If not, an unsecured option such as a personal loan may be worth comparing. |
| Do I want to take on another required monthly mortgage payment? | Eligible older homeowners who want to avoid required monthly mortgage payments may want to consider a reverse mortgage. |
→ Read more: Reverse mortgage vs HELOC vs home equity loan: Comparing your home equity options
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, including property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
Is a HELOC a good idea for you?
Whether a HELOC is a good idea depends on your financial goals and if you’re comfortable with its costs and payment requirements. Before deciding, consider how much you expect to borrow, when you’ll need the money, and how you plan to repay the balance.
It’s also worth comparing those factors across your other options. For eligible older homeowners, a reverse mortgage offers a different payment structure, with no required monthly principal and interest payments.
If a reverse mortgage is one of the options you’re considering, use Finance of America’s reverse mortgage calculator to estimate how much home equity you may be able to access.
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, including property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
FAQs about HELOCs
How much can you borrow with a HELOC?
The amount depends on factors such as your home’s market value, available equity, existing mortgage debt, income, credit profile, and the lender’s requirements.
Can you pay off a HELOC early?
Generally, yes. However, some lenders may charge a fee if you pay off and close the HELOC within a certain period, so check your loan terms.
What happens if you can’t make HELOC payments?
Missed payments may lead to fees, hurt your credit, and eventually result in default. Because your home secures the HELOC, continued missed payments could ultimately lead to foreclosure.
What happens to a HELOC if your home value decreases?
A significant decline in your home’s value may cause a lender to reduce or freeze your available credit, depending on the circumstances and applicable requirements. You’re still responsible for repaying any amount you’ve already borrowed.
Does a HELOC affect your credit score?
It may. Applying typically involves a hard credit inquiry, and your payment history and other credit factors may affect your score after you open the HELOC.
Can you sell your home if you have a HELOC?
Yes. However, because your home secures the HELOC, you generally must repay the outstanding balance when you sell.
Is HELOC interest tax deductible?
HELOC interest may be tax deductible if the funds are used to buy, build, or substantially improve the home securing the loan, subject to IRS requirements and limitations. Consult a tax professional about whether the interest is deductible in your situation.
About the author

is a Senior Web Content Writer at Finance of America and a journalist with more than 20 years of experience specializing in business, and technology. Her work has been published in The Wall Street Journal, The Financial Times, and numerous other leading outlets.
Disclaimer
This article is intended for general informational and educational purposes only and should not be construed as financial or tax advice. For tax advice, please consult a tax professional. For more information about whether a reverse mortgage fits into your retirement strategy, you should consult your financial advisor.