Explore by category
What are the three types of reverse mortgages?
In this article:
- HECM (Home Equity Conversion Mortgage): The most common reverse mortgage
- Proprietary reverse mortgages (jumbo): For higher-value homes or younger borrowers
- Single-purpose reverse mortgage: Designed for specific expenses
- HECM vs jumbo reverse mortgage
- Choosing the right reverse mortgage type for you
- Next steps with Finance of America
- Frequently asked questions about reverse mortgages
Quick Answer: The three types of reverse mortgages are Home Equity Conversion Mortgages (HECMs), proprietary reverse mortgages, and single-purpose reverse mortgages. Each type may have different eligibility requirements, loan terms, and borrower safeguards.
Key points
The most common type of reverse mortgage, the HECM, is insured by the FHA and has specific rules and borrower safeguards set by federal agencies.
Proprietary reverse mortgages allow lenders to offer more flexible terms, including potentially higher borrowing limits or lower age requirements.
Single-purpose reverse mortgages, the least common type, are offered by local agencies, governments, and nonprofits for a single defined purpose.
The reverse mortgage industry is growing rapidly. According to HousingWire, total reverse mortgage lending rose from $6.25 billion in 2023 to $9.65 billion in 2025. As reverse mortgages gain more attention, it’s more important than ever for older homeowners to understand how these loans work.
Many people assume all reverse mortgages are the same, but there are actually several types: HECM, proprietary, and single-purpose reverse mortgages. Each of the three types of reverse mortgages may have different requirements and loan terms, so understanding how they vary is important for making an informed decision.
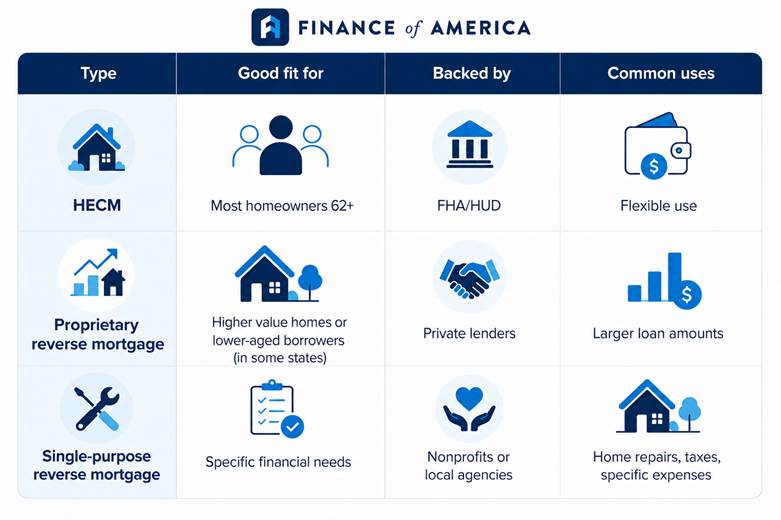
This article will explore the three types in more detail, but this chart outlines the core differences:
→ Learn more: What is a reverse mortgage and how do they work?
HECM (Home Equity Conversion Mortgage): The most common reverse mortgage
HECMs are insured by the FHA and regulated by the U.S. Department of Housing and Urban Development (HUD), which provides borrower safeguards and standardizes lending rules. HECMs may be available in multiple payout options, including a line-of-credit option, lump sum, and monthly payouts. Options vary depending on whether you choose a fixed- or adjustable-rate HECM.
To be eligible, homeowners must meet several guidelines, including:
- Be age 62 or older
- Live in the home as their primary residence
- Own the home outright or have enough equity to pay off any existing mortgage or other required liens with HECM proceeds or other funds at closing
- Meet financial assessment requirements, including demonstrating the ability to meet ongoing property-related expenses
- Continue paying property taxes, homeowners insurance, and other required property charges, and maintain the home
- Complete counseling with a HUD-certified HECM housing counselor to understand the loan’s costs, responsibilities, repayment requirements, and alternatives
Like other reverse mortgages, HECMs allow homeowners to convert a portion of their home equity into cash without required monthly mortgage payments. Repayment is generally deferred until the borrower sells the home, permanently moves out, or passes away. However, borrowers must maintain the home as their primary residence, keep it in good repair, and pay property taxes, fees, and homeowners insurance.
→ Learn more: What is a HECM loan and how do they work?
Understanding FHA safeguards for HECM borrowers
HECM loans are also subject to a federal lending limit, known as the maximum claim amount. For 2026, the national HECM lending limit is $1,249,125, meaning homeowners cannot borrow more than that amount, regardless of their home equity. Other factors that may affect how much can be borrowed include age, interest rate, appraised value, and the remaining balance on a traditional mortgage.
One of the key protections offered through HECM loans is the non-recourse feature.1 This means neither the borrower nor their heirs will owe more than the home’s value when the loan becomes due, even if the loan balance eventually exceeds the property value.
→ Learn more about reverse mortgage requirements: What are reverse mortgage eligibility requirements?
Proprietary reverse mortgages (jumbo): For higher-value homes or younger borrowers
Proprietary reverse mortgages are a category of reverse mortgages offered by individual lenders rather than government-backed programs. Because they are not insured by the FHA or regulated under HECM rules, lenders have more flexibility on loan terms.
Common features of proprietary reverse mortgages vary by product, but may include:
- Potentially higher borrowing limits than federally insured HECM loans (called jumbo reverse mortgages)
- Eligibility for borrowers as young as 55 in some states
- Not subject to FHA mortgage insurance premiums (MIPs); costs and requirements vary by product
- Greater flexibility in loan structures and payout options
Because these are private loans, borrower protections, fees, and repayment terms may vary, so make sure you fully understand the loan if you choose a proprietary reverse mortgage. Unlike HECM loans, HUD counseling is not required for proprietary mortgages, though many reputable lenders recommend it.
Proprietary reverse mortgages may also not require upfront or ongoing mortgage insurance premiums, which may reduce certain loan costs. However, interest rates and fees may be higher, depending on the lender and loan structure.
Some lenders also offer specialized products with different eligibility standards, age requirements, or property guidelines depending on the borrower’s financial situation and home value.
Another major difference is eligibility age. While HECMs require borrowers to be age 62 or older, some proprietary reverse mortgage products extend eligibility to borrowers as young as 55 in some states.
Jumbo reverse mortgages
Jumbo reverse mortgages are designed for homeowners with higher-value properties that exceed the FHA lending limits for HECM loans. Depending on the lender, some borrowers may be allowed to access more of their home equity or be eligible even if under 62.
Not all jumbo mortgages have the same terms or eligibility requirements, so make sure to review loan documents and talk to your lender to ensure you understand how the loan you’re considering works.
Learn more about HomeSafe, a suite of jumbo reverse mortgage options from Finance of America.
The HomeSafe reverse mortgage is a proprietary product of Finance of America and is not related to the Home Equity Conversion Mortgage (HECM) program. HomeSafe products are only available in certain states. Please contact us for a complete list of availability.
Single-purpose reverse mortgage: Designed for specific expenses
Single-purpose reverse mortgages are the least common type. These are typically offered by local governments, nonprofit organizations, or community programs and have limited availability. Unlike HECMs and proprietary reverse mortgages, which allow borrowers to use their funds for a variety of needs, payouts from single-purpose reverse mortgages generally can be used only for specific, approved purposes.
Single-purpose reverse mortgages often have lower costs and may have less strict financial requirements than other reverse mortgage options. However, they are not available in all areas. These loans are commonly offered to older, lower-income homeowners for things like:
- Home repairs or accessibility upgrades
- Property taxes
- Homeowners insurance
- Deferred home maintenance
- Energy efficiency improvements
Eligibility requirements vary by product, and borrowers typically cannot use the money for general living expenses, travel, or to get a handle on debt, like they could with other reverse mortgages.
HECM vs jumbo reverse mortgage
For most homeowners comparing reverse mortgage options, the decision typically comes down to a federally insured HECM loan or a proprietary jumbo reverse mortgage. While both allow homeowners to convert home equity into cash without required monthly mortgage payments, they differ in borrowing limits, eligibility requirements, costs, and borrower protections.
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, including property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
We didn’t include single-purpose reverse mortgages in this comparison because they are much less common and their requirements, loan limits, and approved uses can vary significantly from location to location.
Let’s break down the main differences:
| Feature | HECM reverse mortgage | Jumbo reverse mortgage (proprietary) |
| Backing | Federally insured by FHA/HUD | Private lender product |
| Age requirement | Homeowners age 62+ | Varies; may be available to homeowners age 55+ in some states |
| Maximum loan amount | Subject to FHA lending limits | Higher borrowing limits for high-value homes |
| Mortgage insurance premiums (MIP) | Required upfront and annually | Not subject to FHA MIP; other costs vary by product |
| HUD counseling requirement | Required with a HUD-certified counselor | Often required by the lender, but not mandatory by law |
| Government safeguards | Includes FHA borrower safeguards and standardized rules | Not FHA-insured; safeguards and requirements vary by product |
| Non-recourse protection | Included | Often included, but terms vary by lender |
| Interest rates | Fixed or adjustable rates may be available based on current market rates | May be higher depending on the lender and loan type |
| Property types allowed | Must meet FHA property requirements | May offer more flexibility |
| Suited for | Most eligible homeowners 62+ | Higher-value homes that exceed FHA lending limits, or younger borrowers in some states |
Understanding fees and closing costs
The cost of a reverse mortgage can vary significantly based on the type of loan you choose. One of the biggest differences between HECM and proprietary reverse mortgages is whether you have to pay mortgage insurance.
Because the FHA federally insures HECM loans, borrowers are required to pay mortgage insurance premiums. These costs typically include both an upfront payment at closing and an ongoing annual premium that accrues over time. In exchange, borrowers receive federal safeguards, including non-recourse protection1.
Proprietary reverse mortgages generally do not require FHA mortgage insurance premiums. This may reduce upfront costs for some borrowers, particularly homeowners with higher-value properties. However, proprietary loans may carry higher interest rates and may not offer the same borrower safeguards.
Another important factor to understand is negative amortization. Since reverse mortgage borrowers are not required to make monthly mortgage payments, interest and fees accrue on the loan balance over time. As the amount owed grows, the homeowner’s remaining equity gradually decreases. This applies to all types of reverse mortgages.
→ Learn more about reverse mortgage costs and fees.
Choosing the right reverse mortgage type for you
In general, a HECM reverse mortgage is often the best fit for homeowners who are okay with the federal lending limit and want federally backed protections, standardized loan rules, and flexible payout options.
A proprietary or jumbo reverse mortgage may make more sense for homeowners with higher-value properties who want to access more equity than FHA lending limits allow.
A single-purpose reverse mortgage may be worth considering for homeowners who need help covering a specific expense, such as home repairs or property taxes, and who are eligible for a local nonprofit or government program.
Here’s a quick list to guide you in the right direction:
- If you’re 62+ with a home worth less than $1.25M AND want federal protections → HECM is worth considering.
- If your home is worth over $1.25M or you need more than the HECM limit → Proprietary may be a better fit.
- If you’re 55–61 and own a high-value home → Consider proprietary or single-purpose options.
- If you need funds for a specific expense (home repair, property tax) and have limited income → Check for single-purpose options in your state.
- If you want flexibility AND federal safeguards → HECM with a line-of-credit payout could be an option.
Next steps with Finance of America
Reverse mortgages are not one-size-fits-all loans. From federally insured HECMs to jumbo proprietary products and single-purpose loans, each option is designed for different financial situations and goals. Understanding how these loans work and how they differ may help homeowners and their families make more informed decisions about using home equity in retirement.
For many borrowers, the next step is determining how much cash they may be able to access.
→ Use our reverse mortgage calculator to see how much you may be eligible for.
Frequently asked questions about reverse mortgages
How much equity is required for a reverse mortgage?
There is no single percentage of home equity required for every reverse mortgage. For a HECM, you generally must own your home outright or have enough equity to pay off your current mortgage balance at closing using reverse mortgage proceeds or other funds. How much you may be able to borrow depends on factors such as your age, home value, and interest rates.
→ Learn more: How much equity is needed for a reverse mortgage?
Who owns the house with a reverse mortgage?
You remain the owner of your home when you have a reverse mortgage. The title stays in your name, just as it does with a traditional mortgage. You must continue meeting loan requirements, including living in the home as a primary residence and staying current on property taxes, homeowners insurance, and maintenance.
→ Learn more: Who owns the house in a reverse mortgage?
Can I cancel a reverse mortgage after closing?
Yes, in some cases. For most HECMs, you have three business days after closing to cancel the loan without penalty, which is known as the three-day right of rescission. You must notify the lender in writing that you are canceling the loan within that period. The right of rescission does not apply to a HECM for Purchase, and cancellation rights for proprietary reverse mortgages may vary.
→ Learn more: How to get out of a reverse mortgage if your circumstances change
What happens to my spouse if they aren’t on the reverse mortgage?
It depends on whether your spouse is considered an eligible non-borrowing spouse under HUD rules and the type of reverse mortgage. For HECMs, the spouse must meet specific requirements, including continuing to use the home as their principal residence and meeting applicable loan obligations. An eligible non-borrowing spouse does not receive additional reverse mortgage proceeds.
Do I have to take all the reverse mortgage money at once?
No. You may be eligible to receive your loan proceeds as a lump sum, monthly payouts, a line of credit, or a combination of those options. Available payout options can vary by location, age, product type, and whether the loan has a fixed or adjustable interest rate.
→ Learn more: Understanding reverse mortgage payout options
What happens if my home value drops after I get a reverse mortgage?
A drop in your home’s value generally does not cause a reverse mortgage to become due. For HECMs, FHA insurance provides additional protection because the loan is non-recourse1, meaning you or your heirs generally won’t owe more than the home’s value when it is sold to repay the loan. Proprietary reverse mortgages may offer similar protections, but terms vary by product.
1 Non-recourse means that you, or your estate, can’t owe more than the value of your home when the loan becomes due and the home is sold. Non-recourse means that if you default on the loan, or if the loan cannot otherwise be repaid, the lender cannot look to your other assets (or your estate’s assets) to meet the outstanding balance on your loan.
About the author

is the Web Content Manager at Finance of America and a journalist with more than 10 years of experience whose work has appeared in MoneyWise, MSN, Yahoo! Finance, and The Motley Fool. She specializes in making complex financial topics accessible and is passionate about advancing financial literacy.
Disclaimer
This article is intended for general informational and educational purposes only and should not be construed as financial or tax advice. For tax advice, please consult a tax professional. For more information about whether a reverse mortgage fits into your retirement strategy, you should consult your financial advisor.