Explore by category
Who owns the house in a reverse mortgage?
In this article:
- How does a reverse mortgage affect home ownership?
- Do you own your home with a reverse mortgage loan?
- Can you lose the house with a reverse mortgage?
- Can I give my house to my children or heirs if I have a reverse mortgage?
- Can I sell the home if I have a reverse mortgage?
- How are reverse mortgage loans paid back?
- What to remember about home ownership and reverse mortgages
- Frequently asked questions about home ownership with reverse mortgages
Quick Answer: You own your home with a reverse mortgage. Your name remains on the title, while the lender holds a lien on the property to secure repayment.
Key Points
Having a reverse mortgage does not prevent you from selling your home or leaving it to your heirs.
Borrowers must continue to meet loan requirements, including living in the home as a principal residence, paying property taxes and homeowners insurance, and maintaining the property.
The loan becomes due after certain events, but that does not mean the lender immediately takes the home.
One common misconception about reverse mortgages is that the lender takes ownership of your home. It doesn’t. You remain the homeowner, and your name stays on the title.
What does change is that the lender places a lien on your home to secure repayment of the loan. You also have certain responsibilities as a borrower, and specific events may cause the loan to become due and payable.
So what does that mean for your rights as a homeowner? Below, we’ll explain what you can do with the home, when the loan may become due, what happens if you sell or leave the home to your heirs, and what you need to know if a non-borrowing spouse or someone else lives with you.
→ Take a closer look: Reverse mortgage myths: 14 misconceptions debunked
How does a reverse mortgage affect home ownership?
A reverse mortgage allows older homeowners to access a portion of their home equity without selling the home.
There are three main types of reverse mortgages:
- Home Equity Conversion Mortgages (HECMs): Reverse mortgages insured by the Federal Housing Administration (FHA).
- Proprietary reverse mortgages: Privately funded reverse mortgage products that the federal government does not insure.
- Single-purpose reverse mortgages: Loans typically offered by certain state and local governments or nonprofits for a specific approved purpose, such as home repairs or property taxes.
HECMs, the most common type of reverse mortgage, are available to homeowners age 62 and older. Some proprietary reverse mortgage products may be available to borrowers beginning at age 55, depending on the product and state.
Unlike a traditional mortgage, where homeowners make regular payments that reduce the amount owed, a reverse mortgage generally does not require monthly mortgage payments while the loan is in good standing. Instead, the loan balance grows over time as you access funds and as interest and fees accrue.
To learn more, please visit the CFPB’s “Reverse Mortgages: A Discussion Guide.”
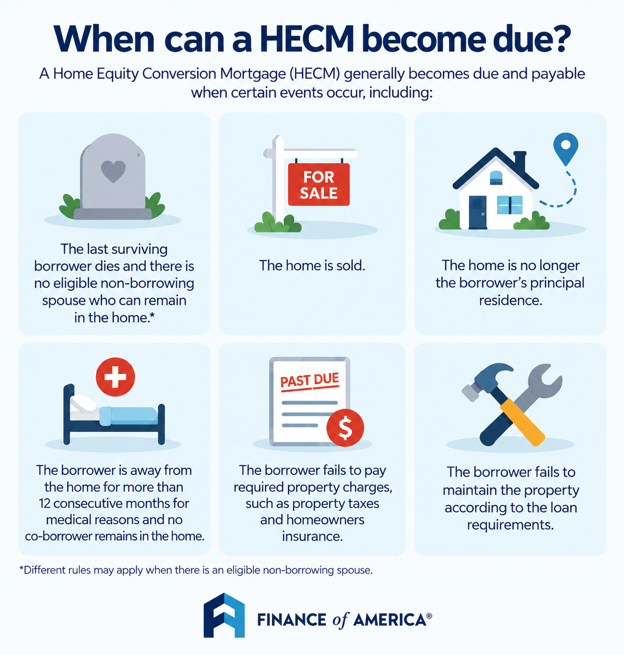
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, including property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
Do you own your home with a reverse mortgage loan?
Yes. When you take out a reverse mortgage, you remain the legal owner of your home, and your name remains on the title.
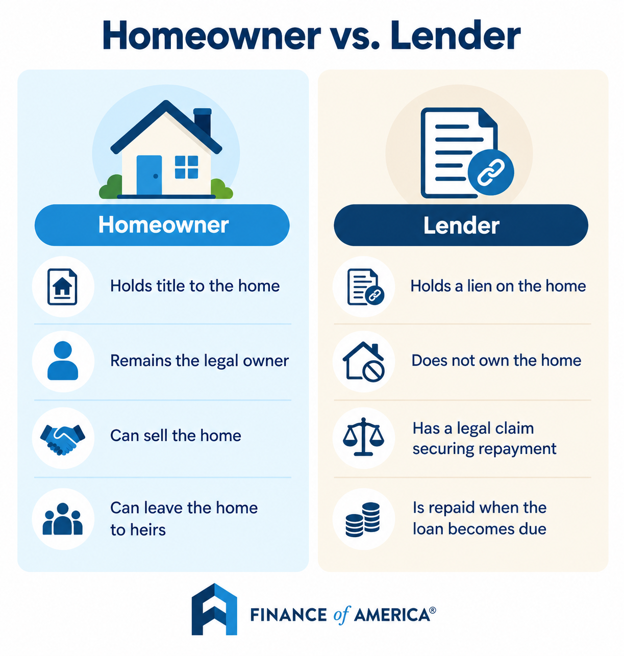
The important distinction is between holding the title and holding a lien.
The title establishes legal ownership of the property. Because you retain title, you continue to own the home.
Meanwhile, the lender holds a lien on the property that secures repayment of the debt. Traditional mortgages also use the home as security for the loan. Holding a lien does not make the lender the owner of your home.
As the homeowner, you may generally continue living in the home, sell it, or leave it to your heirs. Those rights remain subject to the terms of the reverse mortgage.
Here’s a closer look at what holding the title means for you and what holding a lien means for the lender.
Can you lose the house with a reverse mortgage?
Yes. Although you retain ownership of your home, you must continue to meet the terms of the reverse mortgage. A reverse mortgage may become due and payable if you don’t meet the loan requirements or another event triggers repayment.
Homeowners may worry that a decline in their home’s value could also cause the loan to become due. However, a drop in market value by itself generally does not cause a HECM to become due and payable.
When a reverse mortgage does become due, the lender does not immediately take the home. Depending on the circumstances, the borrower, estate, heirs, or other parties with legal title generally have an opportunity to address the debt or resolve the default.
If a borrower defaults on loan requirements and the issue is not resolved, foreclosure may ultimately occur.
Can I give my house to my children or heirs if I have a reverse mortgage?
Yes. Because you retain ownership of the home, you may still leave it to your children or other heirs.
The reverse mortgage generally becomes due upon the last surviving borrower’s death. However, different rules may apply when an eligible non-borrowing spouse is present. Heirs may choose to keep the home and repay the loan, or sell it and use the proceeds to repay the loan. If the home is sold for more than the amount owed, any remaining equity belongs to the estate or heirs.
HECMs are also non-recourse loans. In general, that means neither the borrower nor the estate is personally liable for HECM debt beyond the home’s value.1
→ Learn more: Are heirs responsible for reverse mortgage debt?
Can I sell the home if I have a reverse mortgage?
Yes. Having a reverse mortgage does not prevent you from selling your home.
Because you retain title, you may decide to sell the property while the reverse mortgage is outstanding. When you sell, the reverse mortgage balance—including the amount borrowed, interest accrued, and fees added—must be repaid.
The process generally works like this:
- You list and sell the home.
- The reverse mortgage is repaid from the sale proceeds.
- Any remaining equity belongs to you.
Here’s how that might look in practice. Kerry, age 75, has a reverse mortgage but later decides she wants to downsize and move closer to family. She may sell her home and use part of the proceeds to repay the outstanding balance on the reverse mortgage. Any equity remaining after the loan and other costs are paid belongs to Kerry.
In other words, getting a reverse mortgage doesn’t necessarily lock you into your current home forever. If your plans change later, selling the home remains an option.
For a real-world perspective, read about the experiences of Finance of America customers who have used reverse mortgages.
How are reverse mortgage loans paid back?
A reverse mortgage must be repaid when the loan becomes due. How that happens depends on the circumstances.
For example, a homeowner who decides to move may sell the property and repay the reverse mortgage from the sale proceeds. In other situations, the borrower, estate, or heirs may use other funds to satisfy the loan.
Because repayment rules and options vary depending on why the loan became due and who is handling the property, it’s important to understand the process before making a decision.
→ Read more: How do you repay a reverse mortgage?
What to remember about home ownership and reverse mortgages
Taking out a reverse mortgage does not transfer ownership of your home to the lender. You remain the homeowner and keep your name on the title, while the lender holds a lien that secures repayment of the loan.
That means you continue to have many of the rights that come with home ownership, including the ability to sell the home or leave it to your heirs. You also continue to have responsibilities, such as meeting the occupancy, property tax, insurance, and maintenance requirements that apply to your loan.
Understanding both sides of that equation—your rights as the homeowner and your responsibilities as a borrower—could help you make a more informed decision about whether a reverse mortgage fits your plans.
Want to see how much of your home equity you may be able to access? Use our reverse mortgage calculator for an estimate.
Frequently asked questions about home ownership with reverse mortgages
Do I still own my home if I put it into a living trust and have a reverse mortgage?
Yes. A home with a HECM may be transferred into an eligible living trust without causing the loan to become due and payable. Because the trust must meet certain requirements, check with your loan servicer before making the transfer.
Can I add my spouse to the title after I get a reverse mortgage?
You may be able to add a spouse to the title, but doing so does not make them a borrower on the reverse mortgage. Check with your loan servicer before making changes to the title.
What happens if I move out temporarily for medical reasons or rehab?
A temporary medical absence does not necessarily cause a HECM to become due. However, the loan may become due if you’re away for more than 12 consecutive months for medical reasons and no co-borrower remains in the home.
If I pay off my reverse mortgage early, do I fully own my house again?
You already own your home while you have a reverse mortgage. Paying off the loan satisfies the debt and releases the reverse mortgage lien.
Can I rent out my home if I have a reverse mortgage?
Possibly, as long as the home remains your principal residence and you continue to meet the terms of the loan. Moving out and converting the home to a rental may cause the loan to become due.
Can someone else live with me if I have a reverse mortgage?
Yes. Having an adult child, caregiver, or another person live with you does not typically affect your reverse mortgage as long as you continue to meet the loan requirements. However, living in the home does not make that person a borrower or automatically give them the right to remain after the loan becomes due.
About the author

is a Senior Web Content Writer at Finance of America and a journalist with more than 20 years of experience specializing in business, and technology. Her work has been published in The Wall Street Journal, The Financial Times, and numerous other leading outlets.
Disclaimer
This article is intended for general informational and educational purposes only and should not be construed as financial or tax advice. For tax advice, please consult a tax professional. For more information about whether a reverse mortgage fits into your retirement strategy, you should consult your financial advisor.