Explore by category
Are heirs responsible for reverse mortgage debt?
In this article:
Quick answer: Heirs are never personally responsible for repaying a reverse mortgage because they aren’t borrowers on the loan. However, if they inherit the home, they’ll need to decide how to resolve the reverse mortgage.
Key Points
When a reverse mortgage becomes due and payable, heirs may need to decide whether to keep the home, sell it, or allow the lender to take possession.
Home Equity Conversion Mortgages (HECMs) have specific rules and safeguards for heirs, including provisions for what happens if the loan balance exceeds the home’s value.
A surviving co-borrower or eligible non-borrowing spouse may have different rights than other heirs or occupants.
Reverse mortgages can raise important questions about what happens to the loan and the home when repayment becomes due. Borrowers may want to understand what the loan could mean for their heirs, while heirs may want to know whether they’ll be responsible for the debt and what options they’ll have for the home.
How the process works depends in part on the type of reverse mortgage involved. One common type of reverse mortgage, called a Home Equity Conversion Mortgage (HECM), is insured by the Federal Housing Administration (FHA) and comes with federal rules and safeguards. Proprietary reverse mortgages may work differently, particularly regarding repayment and the options available for the home.
Other circumstances may matter as well, including the reverse mortgage balance compared with the home’s value and whether a surviving spouse still lives there. Understanding how the debt is handled—and what choices heirs may have—can help borrowers and their families know what to expect.
Do heirs have to pay back a reverse mortgage?
Heirs are never personally responsible for repaying a reverse mortgage because they are not parties to the loan. However, they may still need to decide how to resolve the loan. HECMs are non-recourse loans, meaning the lender generally can’t seek repayment of any shortfall from the borrower’s estate if the home isn’t worth enough to repay the loan. Proprietary reverse mortgages may also be non-recourse, but protections vary by lender and loan terms.1
If the home’s value exceeds what’s needed to repay the reverse mortgage and applicable costs, any remaining equity stays with the borrower’s estate.
A reverse mortgage generally becomes due and payable when certain events occur, including the last borrower’s death, sale of the home, permanent move-out, or failure to meet loan requirements.
→ Learn more: How do you repay a reverse mortgage?
What happens if you inherit a home with a reverse mortgage?
If you inherit a home with a reverse mortgage that has become due and payable, contact the loan servicer promptly to confirm the loan balance, deadlines, and available options.
For a HECM, the servicer sends a due-and-payable notice after the borrower and any co-borrowers or eligible non-borrowing spouse have died. The notice includes the amount owed, options for satisfying the debt, and applicable deadlines. Once heirs receive the notice, they generally have 30 days to take action to buy, sell, or turn the home over to the lender to satisfy the debt. The timeline may be extended for up to six months to allow heirs to sell the home or obtain financing to purchase it.
Heirs should also ask the servicer about responsibilities for the property while the loan is being resolved, including property taxes, homeowners insurance, and maintenance.
What happens next depends largely on what you want to do with the home.
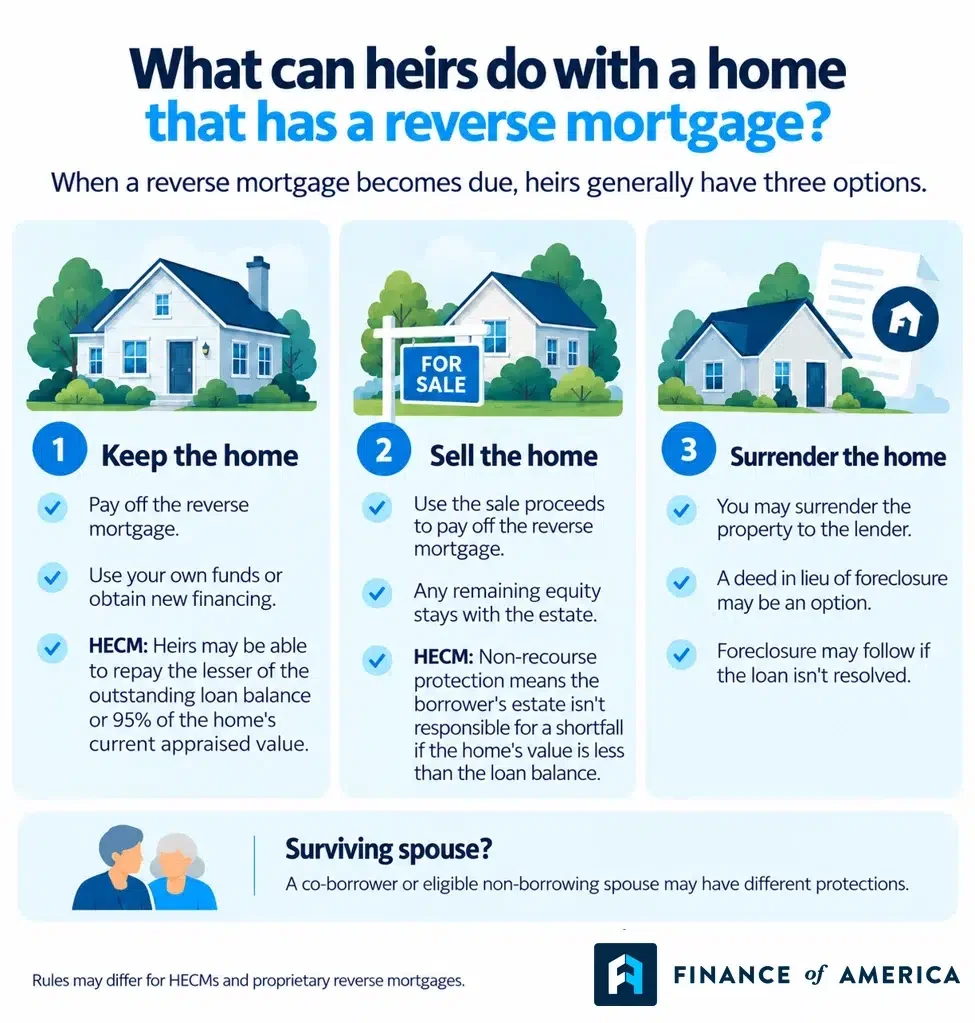
Keep the home
If you want to keep the family home, you’ll need to pay off the reverse mortgage. You may use your own funds or obtain new financing.
For a HECM, heirs may be able to repay the lesser of the full loan balance or 95% of the home’s current appraised value. Proprietary reverse mortgages have their own repayment requirements, so you should review the loan documents and contact the servicer for details.
→ Read more: What are the three types of reverse mortgage loans?
Sell the home
You may also choose to sell the home and use the proceeds to pay off the reverse mortgage. If the home sells for more than the reverse mortgage balance and applicable costs, any remaining equity belongs to with the estate.
Because HECMs are non-recourse loans, the borrower’s estate isn’t responsible for a shortfall if the loan balance exceeds the home’s market value. FHA mortgage insurance covers the lender against that loss.1
Proprietary reverse mortgages aren’t FHA-insured, so you’ll need to review the loan terms to see what safeguards and repayment requirements apply.
To learn more, please visit the CFPB’s “Reverse Mortgages: A Discussion Guide.”
Allow the lender to take possession
Another option is to surrender the property to the lender.
One way to do this is through a deed-in-lieu of foreclosure, which allows you to transfer ownership of the home to the lender rather than go through foreclosure. Whether this option is available depends on your circumstances, the lender, and the loan terms.
If you don’t take steps to repay the reverse mortgage, the lender may ultimately proceed with foreclosure. However, foreclosure doesn’t happen immediately, and the lender must follow a process that includes required notices and opportunities to resolve the loan.
→ Take a closer look: Reverse mortgage foreclosure: How it happens and what to do next
What if a spouse is still living in the home?
A surviving spouse may be able to remain in the home after a reverse mortgage borrower dies. What happens next depends in part on whether the spouse is a co-borrower or an eligible non-borrowing spouse.
A co-borrower is a spouse who is also a borrower on the reverse mortgage. If the surviving spouse is a co-borrower, the loan generally doesn’t become due just because the other borrower dies, as long as the loan requirements continue to be met. For a HECM, a surviving co-borrower may also continue to receive available loan proceeds.
A spouse who is considered “non-borrowing” was married to the borrower when the reverse mortgage was taken out, remained married to the borrower until their death, and isn’t named as a borrower on the loan. For a HECM, a non-borrowing spouse who meets certain requirements may be eligible for a deferral period that allows them to remain in the home after the borrower dies. An eligible non-borrowing spouse generally cannot continue receiving HECM proceeds.
→ Learn more: A non-borrowing spouse’s guide to reverse mortgage
Other relatives or occupants don’t automatically receive the same safeguards simply because they were living in the home when the borrower died.
Planning ahead for your family
Whether you’re considering a reverse mortgage or have inherited a home with one, understanding how the loan may affect your family can help you prepare for important decisions.
For heirs, that means understanding the type of reverse mortgage involved, the available options, and applicable deadlines.
If you have questions about an existing loan or the steps you need to take, contact the loan servicer for more information. If your loan is serviced by Finance of America, call 800-841-5166 or find additional contact information on our website.
For homeowners considering a reverse mortgage, it’s also worth thinking about how borrowing against your home may affect the equity you leave behind.
→ Exploring whether a reverse mortgage might fit your plans? Use our reverse mortgage calculator to estimate how much home equity you may be able to access.
FAQs
Is a reverse mortgage assumable or transferable to heirs?
No, heirs can’t take over a reverse mortgage and continue it under the same terms. If they want to keep the home, they’ll need to repay the loan using their own funds or obtain new financing.
Can heirs refinance a reverse mortgage to keep the home?
Eligible heirs may be able to take out a new loan in their own name to pay off the reverse mortgage and keep the home. This isn’t a transfer of the existing reverse mortgage to the heir. Eligibility and loan terms would depend on the new lender’s requirements.
Does inheriting a home with a reverse mortgage affect the heirs’ credit?
No. A reverse mortgage isn’t the heir’s personal debt, so inheriting a home with one doesn’t affect the heir’s credit by itself. If an heir takes out a new mortgage to pay off the reverse mortgage and keep the home, that new loan would appear on their credit.
Do heirs owe taxes on an inherited home with a reverse mortgage?
Whether heirs owe taxes depends on their individual circumstances and applicable tax rules. Heirs should consult a qualified tax professional for guidance.
What is the biggest reverse mortgage problem for heirs?
No single problem affects every heir. One potential challenge is deciding what to do about the home within the reverse mortgage’s repayment timeline. Understanding the loan balance, deadlines, and available options early may make the process easier to navigate.
1Non-recourse means that you, or your estate, can’t owe more than the value of your home when the loan becomes due and the home is sold. Non-recourse means that if you default on the loan, or if the loan cannot otherwise be repaid, the lender cannot look to your other assets (or your estate’s assets) to meet the outstanding balance on your loan.
About the author

is a Senior Web Content Writer at Finance of America and a journalist with more than 20 years of experience specializing in business, and technology. Her work has been published in The Wall Street Journal, The Financial Times, and numerous other leading outlets.
Disclaimer
This article is intended for general informational and educational purposes only and should not be construed as financial or tax advice. For tax advice, please consult a tax professional. For more information about whether a reverse mortgage fits into your retirement strategy, you should consult your financial advisor.