Explore by category
Reverse mortgage for parents: What adult children need to know
In this article:
- How does a reverse mortgage for parents work?
- Why your parents might consider a reverse mortgage
- What should adult children know about a parent's reverse mortgage?
- How can a reverse mortgage affect your inheritance?
- What happens to the reverse mortgage when a parent dies?
- What alternatives should your parents compare with a reverse mortgage?
- How can you talk to your parents about a reverse mortgage?
- Help your parents make an informed decision
- FAQs about reverse mortgages for parents
Quick answer: A reverse mortgage may help your parents access home equity without selling their home. Whether it fits their needs depends on their finances, housing plans, and long-term goals.
Key points
Parents with a reverse mortgage must continue to meet loan obligations, including paying property taxes and homeowners insurance, maintaining the home, and using it as their principal residence.
Interest and fees increase the loan balance over time, which may leave less home equity for future needs or heirs.
Adult children aren’t personally responsible for repaying a parent’s reverse mortgage simply because they’re heirs, but the loan may affect what happens to the family home.
If your parents are considering a reverse mortgage, you may have questions—or even concerns—about what it could mean for their financial future. Reverse mortgages have had a bad reputation over the years, and misconceptions about how they work may add to the uncertainty.
You might wonder whether your parents will still own their home, what happens if they need to move, or whether you’ll be responsible for the loan after they die. Another concern may be how a reverse mortgage could affect the equity they’ve built and what they eventually leave behind.
Understanding how reverse mortgages work may help you have more productive conversations with your parents about their options. This guide explains why they might consider a reverse mortgage, what it could mean for their home and finances, and what families should understand about inheritance and repayment.
To learn more, please visit the CFPB’s “Reverse Mortgages: A Discussion Guide.”
How does a reverse mortgage for parents work?
A reverse mortgage allows eligible older homeowners to access a portion of their home equity without selling their home or making required monthly mortgage payments. Unlike a traditional mortgage, where the balance decreases as payments are made, a reverse mortgage loan balance grows over time as interest and applicable fees accrue.
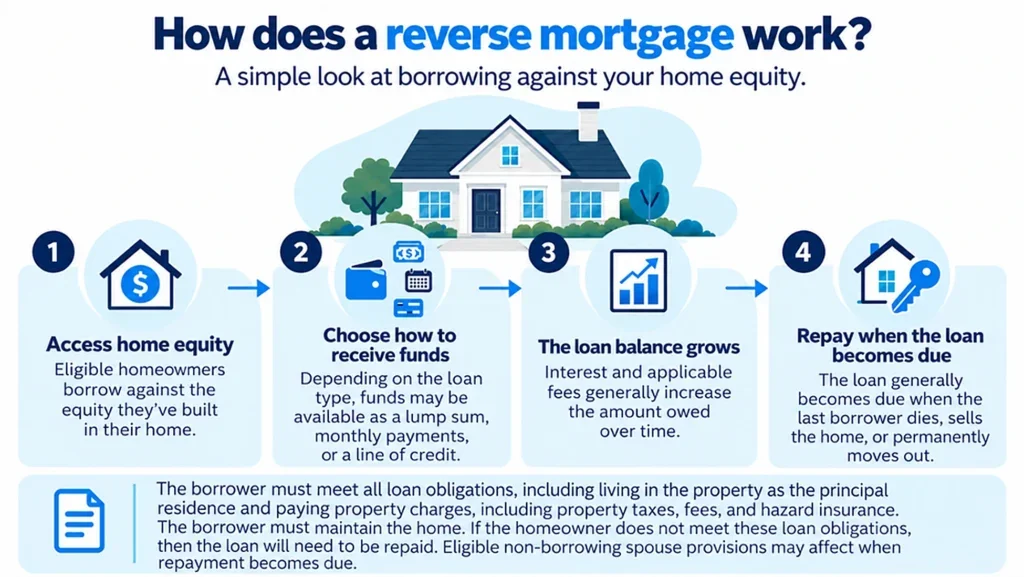
Your parents continue to own their home. However, they must meet the loan’s ongoing requirements, including living in the home as their principal residence, paying required property charges, and maintaining the property.
The most common type of reverse mortgage is a Home Equity Conversion Mortgage (HECM), which is insured by the Federal Housing Administration (FHA) and available to eligible homeowners age 62 and older. Private lenders offer proprietary reverse mortgages, which may have different age and eligibility requirements.
Depending on the loan type, your parents may be able to receive funds as a lump sum, monthly payments, or a line of credit. If your parents are married, whether both are borrowers or one is a non-borrowing spouse may affect what happens if one parent dies or permanently leaves the home.
→ Read more: What is a reverse mortgage and how does it work?
The borrower must meet all loan obligations, including living in the property as the principal residence and paying property charges, including property taxes, fees, and hazard insurance. The borrower must maintain the home. If the homeowner does not meet these loan obligations, then the loan will need to be repaid.
Why your parents might consider a reverse mortgage
Your parents may consider a reverse mortgage for multiple reasons. For some, the priority is reducing monthly expenses. Others may want access to additional funds for current needs or expenses that could arise later.
Some common reasons include:
- Pay off an existing mortgage: Parents may be able to eliminate their monthly mortgage payments by using reverse mortgage funds to pay off the remaining balance.
- Supplement retirement income: Funds from a reverse mortgage could help cover everyday living expenses alongside other sources of retirement income.
- Make home improvements: Reverse mortgage funds may help pay for repairs, home maintenance, or accessibility modifications that make their home safer or easier to navigate.
- Cover healthcare or caregiving expenses: The funds could go toward medical bills, in-home care, or other health-related needs.
- Prepare for future expenses: A reverse mortgage line of credit may provide access to funds for unexpected expenses or other needs later in retirement.
- Remain in their home: A reverse mortgage allows eligible homeowners to access home equity without selling the home they want to continue living in.
Understanding what your parents hope to accomplish can help you have a more informed conversation about whether a reverse mortgage aligns with their priorities.
→ Explore further: Understanding reverse mortgage payout options
The right to remain in the home is contingent on paying property taxes and homeowner’s insurance, maintaining the home, and complying with the loan terms.
What should adult children know about a parent’s reverse mortgage?
A reverse mortgage may affect more than your parents’ monthly finances. It may also impact their long-term plans, the equity they have available for future needs, and what happens to the family home if their circumstances change.
Here are some important considerations to keep in mind as you discuss the decision with your parents.
Your parents still own the home
One common misconception about reverse mortgages is that the lender takes ownership of the home. In reality, a reverse mortgage is a loan secured by the property, not a sale of the home to the lender.
Your parents retain title and ownership, just as they would with a traditional mortgage. They may continue living in the home as long as they meet the loan’s requirements.
→ Take a closer look: Who owns the house in a reverse mortgage?
Your parents still have ongoing responsibilities
Although reverse mortgages don’t require monthly principal and interest payments, your parents remain responsible for the ongoing costs and obligations of homeownership.
Your parents must continue to pay property taxes and homeowners insurance, maintain the property, and use the home as their principal residence. Depending on the property and loan terms, other required charges may apply.
If your parents fail to meet these obligations, the loan may become due and payable. If the issue isn’t resolved, the lender may ultimately proceed with foreclosure. Understanding these responsibilities before closing is important, particularly if your parents expect their housing expenses or ability to maintain the home to change over time.
→ Learn more: Reverse mortgage foreclosure: How it happens and what to do next
Your parents’ housing plans matter
A reverse mortgage is generally intended for homeowners who plan to remain in their home as their primary residence. If your parents expect to sell or move in the near future, they should consider the loan’s upfront costs and repayment requirements.
If their needs change and they permanently move into an assisted living facility or nursing home, the reverse mortgage may become due and payable. The same generally applies if they sell the home or move out for other reasons without intending to return.
Whether both parents are borrowers matters
If your parents are married, whether both are borrowers or only one spouse is named on the loan may affect what happens when one of them dies or permanently leaves the home.
For FHA-insured HECMs, an eligible non-borrowing spouse may be able to remain in the home after the borrowing spouse passes away without the loan immediately becoming due and payable. This safeguard, known as a deferral, is subject to specific eligibility conditions and ongoing requirements.
For example, the spouse must have been married to the borrower at the time the loan closed and remain married until the borrower’s death. The spouse must also meet applicable occupancy and other requirements. During a deferral period, the non-borrowing spouse generally cannot receive additional loan advances.
These safeguards aren’t automatic for every spouse or every type of reverse mortgage. If only one parent will be a borrower, your family should understand what safeguards may apply before the loan closes.
→ Explore further: The non-borrowing spouse’s guide to reverse mortgage
An adult child living in the home isn’t automatically protected
If you or one of your siblings lives with your parents, it’s important to understand that residing there doesn’t automatically make you a borrower or give you the right to remain in the home after the reverse mortgage becomes due.
For example, if the last borrower dies, an adult child living in the property won’t have the same safeguards that may apply to an eligible non-borrowing spouse. The loan will typically need to be resolved, even if the adult child has lived in the home for years.
If you or another family member expects to continue living in the home long term, discuss those plans before your parents take out a reverse mortgage.
How can a reverse mortgage affect your inheritance?
If your parents take out a reverse mortgage, it may affect how much home equity they eventually leave behind. As interest and applicable fees accrue, the growing loan balance may reduce the equity available to heirs, even if your parents don’t borrow additional funds.
Changes in the home’s value also play a role. If the property appreciates, that increase may offset some of the growing loan balance, although appreciation isn’t guaranteed.
It’s important to distinguish between inheriting less home equity and inheriting responsibility for your parents’ debt.
Are adult children responsible for their parents’ reverse mortgage debt?
No. Adult children aren’t personally responsible for repaying their parents’ reverse mortgage simply because they’re heirs. However, if they inherit the home, they’ll need to decide how the loan will be repaid.
HECMs are non-recourse loans, meaning borrowers and their estates aren’t responsible for repaying more than the home’s value, even if the loan balance is higher.1
Some proprietary reverse mortgages also offer non-recourse terms, but the specific requirements may differ from those of FHA-insured HECMs.1 Your parents should review their loan documents to understand what applies.
→ Dive deeper: Are heirs responsible for reverse mortgage debt?
What happens to the reverse mortgage when a parent dies?
When the last borrower on a reverse mortgage dies, the loan generally becomes due and payable. However, that doesn’t mean the lender immediately takes ownership of the home. Heirs typically have options for resolving the loan, subject to applicable requirements and deadlines.
Depending on the circumstances, heirs may:
- Sell the home: The proceeds from the sale may be used to repay the reverse mortgage. Any remaining equity after the loan and applicable selling costs are paid belongs to the estate or heirs.
- Keep the home: They may need to repay the full loan balance with other funds or refinance the loan. For a HECM, if the loan balance exceeds the home’s current appraised value, heirs may be able to keep the property by paying 95% of that value, subject to applicable requirements.
- Turn over the home: If they don’t want to keep or sell the home themselves, they may consider a deed-in-lieu of foreclosure, which transfers ownership to the lender. Availability depends on the circumstances, loan terms, and lender requirements.
For HECMs, heirs generally have 30 days after receiving a due-and-payable notice to decide how to resolve the loan. Extensions of up to six months may be available to allow time to sell the home or arrange financing. Heirs should contact the loan servicer promptly to understand their options and applicable deadlines.
→ For more information: How do you repay a reverse mortgage?
What alternatives should your parents compare with a reverse mortgage?
A reverse mortgage isn’t the only way your parents may be able to access home equity or cover expenses in retirement. The alternatives worth considering depend on their financial needs, ability to make monthly payments, housing plans, and how much equity they want to preserve.
Some options to compare include:
- Home equity loan or home equity line of credit (HELOC): Both allow homeowners to borrow against their home equity without selling the property. A home equity loan generally provides a lump sum, while a HELOC offers revolving access to funds. Both typically require monthly payments, with eligibility based on factors such as income and credit. Interest rates and repayment terms may also differ.
- Cash-out refinance: This replaces an existing mortgage with a larger loan, allowing homeowners to access some of their equity in cash. It also changes the mortgage terms and generally requires monthly principal and interest payments.
- Downsizing or selling the home: Selling may allow your parents to access their equity without taking on another loan. However, they’ll need to consider moving expenses, selling costs, replacement housing costs, and whether a different home would better meet their needs.
- Other retirement resources: Depending on their circumstances, your parents may have access to savings, investments, insurance, government assistance, or family support that could help cover expenses without having to borrow against their home.
→ See also: 9 alternatives to a reverse mortgage
Finance of America does not currently offer home equity loans or HELOCs.
How can you talk to your parents about a reverse mortgage?
Talking with your parents about a reverse mortgage may feel uncomfortable, especially when the conversation involves money, future care needs, or inheritance. Rather than focusing on whether they should or shouldn’t get the loan, try to understand what they hope to accomplish and what matters most to them.
Some questions that may help guide the conversation include:
- What are you hoping a reverse mortgage will accomplish?
- How long do you plan to stay in your home?
- Will you be able to keep up with property taxes, homeowners insurance, maintenance, and other housing expenses?
- What would happen if your health or housing needs changed?
- Will both spouses be borrowers? If not, what safeguards might apply?
- How important is preserving home equity or keeping the home in the family?
- What other financial options have you considered?
- Do you understand when the loan becomes due and what happens next?
The goal isn’t to take the decision out of your parents’ hands, but to help everyone understand their priorities and expectations. Your parents may also choose to involve a financial advisor, estate-planning professional, or another trusted person.
If they’re considering a HECM, they’ll also need to complete a HUD-certified counseling session. This provides an opportunity to discuss the loan’s features, costs, obligations, and alternatives with a certified counselor.
Help your parents make an informed decision
A reverse mortgage is a significant financial decision that may affect your parents’ retirement finances, housing plans, and the equity they eventually leave behind.
As an adult child, you can support your parents by helping them understand the loan’s costs, obligations, and alternatives. Ultimately, the decision belongs to your parents and should reflect their needs and priorities.
If your parents want to take the next step in learning about reverse mortgages, they may use Finance of America’s reverse mortgage calculator to estimate how much home equity they may be eligible to access.
FAQs about reverse mortgages for parents
Can I attend the HUD-approved counseling session with my parent?
Yes, you may be able to attend a HUD-approved reverse mortgage counseling session with your parent if they agree. However, the counselor must ensure that your parent understands the loan and is making an independent, informed decision. Your parent should contact the counseling agency beforehand to ask about its policies for including family members.
Can I be added to my parent’s reverse mortgage after it closes?
You cannot be added as a borrower to an existing reverse mortgage after closing. Becoming a borrower would generally require obtaining a new reverse mortgage, subject to applicable eligibility requirements. For a HECM, borrowers must be at least 62 years old. If you expect to inherit or continue living in the home, discuss your options with your parent and an appropriate professional.
Do adult children need to sign a parent’s reverse mortgage documents?
Adult children aren’t required to sign their parents’ reverse mortgage documents simply because they’re family members or expect to inherit the home. However, if an adult child has an ownership interest in the property or another legal role, the lender may require additional documentation or signatures. The lender or closing professional can explain which parties must sign.
Can a parent get a reverse mortgage without their children’s permission?
Yes. A parent who meets the loan’s eligibility requirements doesn’t need permission from their adult children to obtain a reverse mortgage. However, other parties with legal ownership interests or applicable rights may need to participate in the transaction. While family discussions may be helpful, the decision ultimately belongs to the homeowner.
Will a parent’s reverse mortgage affect Social Security or Medicare?
Reverse mortgage funds generally don’t affect Social Security retirement benefits or Medicare eligibility because they’re loan proceeds, not income. However, needs-based programs such as Supplemental Security Income (SSI) and Medicaid have income and asset rules that may be affected by how reverse mortgage funds are received or retained. Your parents should consult a qualified benefits specialist or financial professional about their circumstances before proceeding.
How can you tell if a reverse mortgage offer is legitimate?
Start by verifying the lender’s credentials and understanding the loan’s costs, terms, and requirements. You may be able to verify a lender’s licensing information through the Nationwide Multistate Licensing System (NMLS) Consumer Access website. Be cautious of anyone who pressures your parents to act quickly, discourages independent advice, or suggests using reverse mortgage funds to purchase unrelated financial products.
→ Learn more: Protecting your home from mortgage scams
1Non-recourse means that if you default on the loan, or if the loan cannot otherwise be repaid, the lender cannot look to your other assets (or your estate’s assets) to meet the outstanding balance on your loan. The loan can only be satisfied through the value of your property.
About the author

is a Senior Web Content Writer at Finance of America and a journalist with more than 20 years of experience specializing in business, and technology. Her work has been published in The Wall Street Journal, The Financial Times, and numerous other leading outlets.
Disclaimer
This article is intended for general informational and educational purposes only and should not be construed as financial or tax advice. For tax advice, please consult a tax professional. For more information about whether a reverse mortgage fits into your retirement strategy, you should consult your financial advisor.